How to Get a Home Appraisal for Divorce in France?
A Paris-specific guide to getting a divorce home appraisal in France: who values the property, what it costs, and how the valuation shapes the buyout.

- Published on
- Updated on
- Reading time
- 16 min read
Introduction
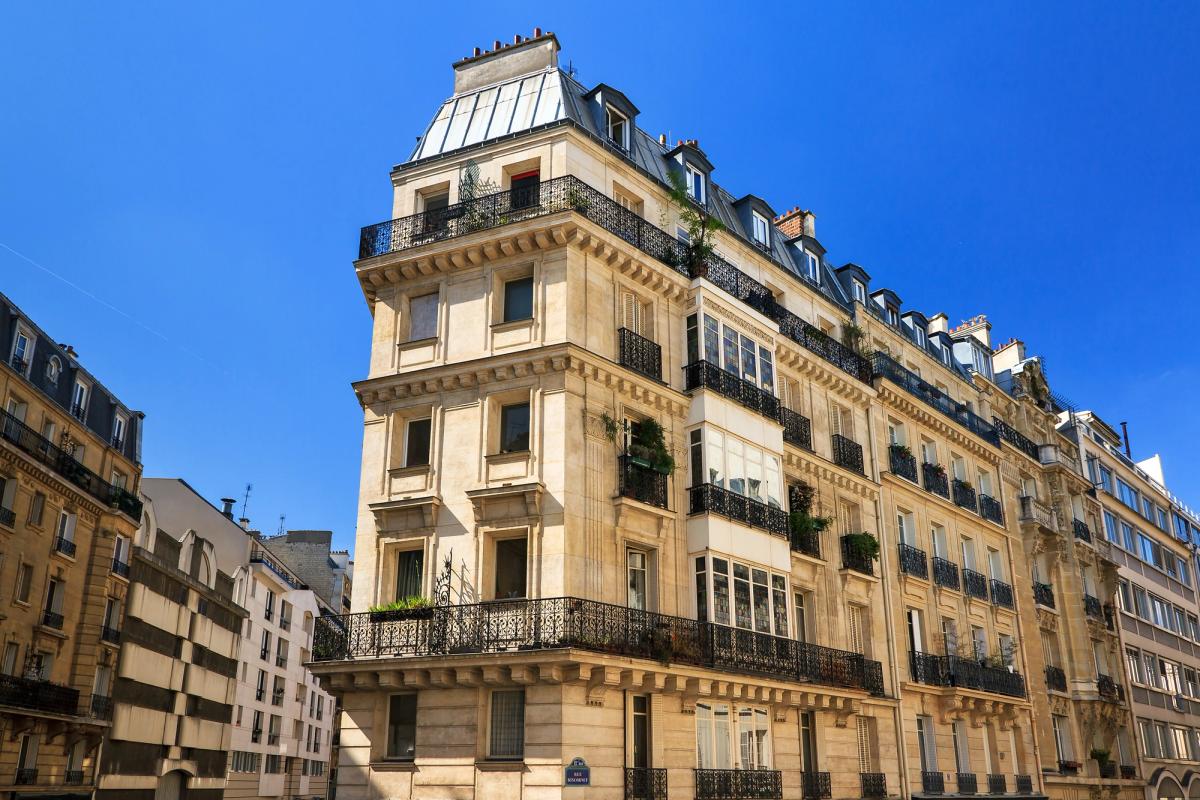
Two spouses can look at the same apartment in the 6th arrondissement and see two different numbers. One remembers what they paid in 2021. The other has seen a similar flat listed for less last month. When the marriage ends, that gap becomes the first real negotiation, and it often plays out across two countries, two sets of lawyers and several time zones.
Search for help in English and most advice assumes the house is in the US: a state-licensed appraiser, a USPAP report, an attorney who orders it. France works differently. There is no MLS, the notaire sits at the centre of every property division, and a Paris valuation depends as much on the floor, the building and the DPE energy rating as on the arrondissement.
This guide explains who can value a Paris property in a divorce, the steps to get it done, what drives the number, what it costs, and what happens when you disagree. It also covers how to handle the process from abroad. It is written for international families, embassy staff, senior professionals and business owners who own property in Paris and need a figure they can rely on.
What Is a Home Appraisal for Divorce in France?
In France, a home appraisal for divorce is a professional estimate of your property's market value (valeur vénale). The notaire uses it to divide the proceeds of a sale, or to calculate what one spouse pays to keep the home.
That figure feeds into the inventory the notary draws up of everything the couple owns and owes, before anything is divided. It also sets the buyout payment, called the soulte, if one of you stays. Real money rides on the number for both of you, so expect it to be read closely.
Home appraisal in the US vs property valuation in France
In the US, a divorce appraisal usually means a state-licensed or certified appraiser producing a report to USPAP standards, often arranged through an attorney. In the UK, it tends to be a RICS valuation by a chartered surveyor. France has neither system.
Three kinds of professionals value property in a French divorce:
- An estate agent (agent immobilier), who gives a market-based opinion called an avis de valeur.
- The notaire, the public officer who handles the division and has access to notarised sales data.
- An independent property expert (expert immobilier), who writes a detailed, reasoned report.
Two differences tend to surprise American and British owners. First, there is no MLS in France, so values rest on recorded notarial sales rather than a shared listings database. Second, "expert immobilier" does not work like a US appraiser licence. Credentials therefore matter: look for recognised qualifications such as REV or TRV, RICS membership, or registration as an expert with a French court of appeal.
Estate agent valuation, notaire valuation or formal expertise?
For most amicable divorces, a valuation from an estate agent or a notaire is enough. The Chambre des notaires de Paris (opens in a new window) itself says that each party can ask a real estate professional, such as an agency or a notaire, for an estimate, and that several estimates are preferable. That runs against advice still circulating online, including in some AI-generated answers, that couples should avoid agents altogether.
The real issue with agent valuations is incentive, not accuracy. An agent who hopes to win the sale mandate may lean optimistic, which is why two or three independent estimates work better than one. A notaire's estimate adds legal weight and access to local sales data, though fees vary and you should ask for a quote first.
A formal expertise is the right tool when the stakes or the tension are high: a contested divorce, a disputed buyout, an unusual property, or a court that needs a reasoned report. Online estimators have a place, but only as a first rough range (they cannot see the damp in the stairwell or the view from the fifth floor).
When do you actually need a property valuation during a divorce?
You need one whenever property owned together has to be divided, sold or bought out. And when the division involves real estate, a notaire must take part, because transfers of property have to be registered with the land registry.
What counts as shared depends on your matrimonial regime:
- Under the default community regime (no marriage contract), each spouse takes back what they owned before the marriage or received by gift or inheritance, and property acquired during the marriage is split in half.
- Under separation of property (séparation de biens), each spouse owns the share written in the title deed, and only property bought together needs dividing. The Paris notaires note that these shares appear in the title deed drawn up at purchase.
If one spouse owns the home alone but joint money paid for the loan or renovations, a valuation may still be needed to settle reimbursement claims between you.
The notaires' English-language guide to dividing property after a divorce in France (opens in a new window) explains how the notary inventories assets and debts before any split.
How to Get a Home Appraisal for Divorce in Paris Step by Step

To get a home appraisal for divorce in Paris, agree on what the valuation is for, choose one or more professionals, give them a complete file, and share the agreed figure with the notaire handling your division.
The six steps below follow the order most Paris cases take. Your timeline may differ if one of you lives abroad or if the divorce is already contested.
Step 1: Decide what the valuation will be used for
The purpose sets the level of report you need. A couple planning to sell together needs a realistic asking price. A spouse buying out the other needs a figure both accept and a bank will finance. A contested case may need a report that holds up in front of a family judge.
Settle this early, ideally with both lawyers in copy. You avoid paying for a formal expertise you do not need, and you avoid relying on a quick estimate that later collapses under challenge.
Step 2: Choose the right property professional
When one spouse wants to buy out the other's share of the family home (opens in a new window), the Paris notaires advise getting an accurate estimate and, where possible, more than one. In practice, many couples ask two or three agencies, or one agency plus the notaire.
When you choose, check three things:
- Independence: no prior relationship with either spouse, and no pressure to sign a sale mandate in exchange for the valuation.
- Local depth: someone who knows your street and your type of building, not just the arrondissement.
- Language: a valuer who can walk you through the report in English if a lawyer or court abroad will read it.
For owners looking for a Paris market valuation, Estate in Paris offers free property valuation services (opens in a new window) based on the property's features, location and recent comparable sales.
Step 3: Prepare the property documents
A valuer can only be as precise as the file allows. Gather these before the visit:
- the title deed (titre de propriété), which shows each spouse's share
- the loi Carrez surface certificate
- the technical diagnostics file (dossier de diagnostic technique), including the DPE energy rating
- the last three general-meeting minutes of the copropriété and recent service-charge statements
- details of any works already voted by the building, such as the façade, roof or lift
- the outstanding loan statement and amortisation schedule
- invoices for renovations done since purchase
This is the French version of the US advice to "provide documentation." The notaire will ask for much of it anyway. Their list of documents for a divorce includes the title deeds and a value notice issued by a real estate professional for each property.
Step 4: Let the professional inspect the property
An in-person visit is needed for a reliable figure. The valuer checks the condition, verifies the surface, notes light, noise and outlook, and looks at the common parts of the building.
Access is often the hardest part. If you are the spouse still living in the flat while the other has moved to London or New York, agree the date in writing and decide who attends. A short video call during the inspection helps nobody feel excluded.
Step 5: Review the comparable sales and valuation
A sound valuation shows its work. Expect a list of recent comparable sales, ideally in the same building or street, with adjustments for floor, condition, outdoor space and energy rating, followed by a value range and a retained figure.
You can check the comparables yourself on the official DVF database of recorded property sales (opens in a new window). It lags a few months behind the market, so a good valuer also draws on the notaires' more recent data and on what is being negotiated in the area right now.
Step 6: Share the valuation with the notaire or advisers
Once you agree on a figure, send the report to the notaire drafting the liquidation statement (état liquidatif) and to both lawyers. If a bank will finance a buyout, send it there too, knowing the bank may commission its own check.
Keep the report dated and clearly labelled. As the section on valuation dates explains, a figure that is many months old may need updating before anything is signed.
How Much Does a Divorce Valuation Cost and How Long Does It Take?
An estate agent valuation is usually free and takes a few days. A notaire or independent expert valuation costs from a few hundred to a few thousand euros and takes one to four weeks. A court-ordered expertise costs more and takes months.
1. Estate agent valuation costs
Most Paris agencies do not charge for a valuation, since they earn their fee when a property sells. The written avis de valeur usually arrives within days of the visit. That makes it the natural first step in an amicable divorce, especially if you gather two or three.
The trade-off is weight. An agent's valuation is a market opinion, not an expert report, so it works best when both spouses accept it.
2. Notaire or formal expert valuation costs
A notaire may value the property as part of the division work. Fees for a stand-alone valuation vary from one office to another, so ask for a written quote.
Independent experts charge by the mission, depending on the property and the report required. As a rough guide from Paris family lawyers, a court-appointed expert valuing a Paris flat costs between €2,000 and €5,000. An amicable expertise commissioned by both spouses usually costs less.
3. How long does a property valuation take?
Timing depends on the route you take:
- Agent valuation: a visit within days, a written estimate shortly after.
- Amicable expertise: typically 2 to 4 weeks from the visit and receipt of documents.
- Court-ordered expertise: several months. A contested Paris divorce involving property in more than one country and an expert valuation often runs well beyond a year.
Plan around the notaire's timetable as well. The valuation should still be recent when the division deed is signed.
4. Who pays for the valuation?
In an amicable divorce, spouses usually split the cost or agree that one of them pays. If each spouse instructs their own professional, each pays their own. For a court-ordered expertise, the party who requests it advances the fees, and the judge decides how they are shared.
| Option | Who prepares it | Typical cost (Paris, 2026) | Typical timing | Weight if you disagree | Best for |
|---|---|---|---|---|---|
| Online estimate | Automated tool | Free | Minutes | Very low | A first rough range |
| Estate agent valuation (avis de valeur) | Local estate agent | Usually free | A few days | Moderate, stronger with several estimates | Amicable divorces, sale pricing |
| Notaire valuation | Notaire | Varies, ask for a quote | Days to weeks | Good, backed by notarial sales data | Buyouts handled by the same notaire |
| Independent expertise | Expert immobilier | Several hundred to a few thousand euros | About 2 to 4 weeks | Strong, reasoned report | Tense cases, unusual properties |
| Court-appointed expertise | Expert or notaire named by the judge | Often €2,000 to €5,000 | Several months | Highest, part of the proceedings | Contested divorces |
What Happens If You and Your Spouse Disagree on the Property Value?

If you disagree, first check that your valuations are comparable, then negotiate or get another opinion. If that fails, a family judge can appoint an expert or a notaire, and a court may have to settle the buyout.
Disagreement is normal. One spouse wants a higher figure for a larger payout, the other a lower one to afford staying. Neither is necessarily acting in bad faith, but both need a way forward.
1. Compare the valuations on the same basis
Before arguing about the numbers, check that they measure the same thing. Agencies often quote different figures: a net price to the seller, a price including agency fees, or a general market price. One person separating from a partner described exactly this on a French legal forum, with three agency estimates built on three different bases.
Line them up on the same basis, the same surface and the same date. The gap often shrinks by itself. If it does not, a midpoint of the range, or a session with a family mediator (médiateur familial), is often enough to close it.
2. Get another professional opinion
When two figures stay far apart, a jointly instructed independent expert can break the deadlock. Agree in advance that you will both accept the result, or that you will settle anywhere within a set range. That agreement is worth more than the report itself.
3. When the dispute becomes part of the legal process
If negotiation fails, the family judge (juge aux affaires familiales) has two tools under article 255 of the Civil Code (opens in a new window). The judge can appoint a qualified professional to draw up an estimated inventory, or appoint a notaire to prepare a draft liquidation and allocation of shares. And if a buyout cannot be agreed amicably, the Paris notaires point out that only the court can decide.
This route adds cost and months. It also takes the decision out of your hands.
4. Which valuation date matters in a French divorce?
Under French law, the value is generally assessed as close as possible to the date the property is divided, not automatically at the divorce or separation date. Article 829 of the Civil Code (opens in a new window) sets the rule: assets are valued at the date of "jouissance divise" fixed in the division deed, and that date must be as close as possible to the division.
A separate date decides what is shared. For divorces other than by mutual consent, the divorce takes effect between the spouses, for their property, from the date the petition is filed. At a spouse's request, the judge can move that date back to when you stopped living and working together.
This is where US-style advice can mislead. American divorce appraisals are sometimes retrospective, valuing the home at the date of separation. In France, a valuation made at the start of a long procedure may need updating before the final deed.
Sell, Keep or Rent Out the Property After the Valuation?
Once the value is agreed, you have four realistic options: one spouse buys out the other, you sell and divide the proceeds, you keep the property jointly for a while, or you rent it out. The right choice depends on cash, financing, timing and tax.
1. One spouse keeps the property and buys out the other
The buyout payment, the soulte, is essentially the departing spouse's share of the equity. Take the agreed value, deduct the outstanding loan, and apply the departing spouse's share.
Take an 80 m² flat valued at €960,000 with €300,000 still owed on the mortgage. The equity is €660,000. With equal shares, the spouse who leaves receives €330,000, and the spouse who stays takes on the whole loan. (This is an illustration, not a valuation.)
The costs are lighter than buying on the open market.
- Buyout: married couples and PACS partners who divide property pay a partition duty (droit de partage) of 1.1% since 1 January 2022. Loan-amendment fees and the notaire's fees come on top.
- Open-market purchase: Paris raised its departmental transfer-duty rate from 4.5% to 5% in 2025, and total acquisition costs on an older property usually reach 7% to 8% of the price.
Financing is the real test. The bank can refuse to release the departing spouse from the loan if it doubts the other can repay alone, and the couple may then have to sell. French lenders apply the HCSF rules: repayments capped at 35% of net income, and a maximum term of 25 years. The average mortgage rate was 3.31% in August 2026, according to the Observatoire Crédit Logement/CSA (opens in a new window).
2. Sell the property and divide the proceeds
Selling gives both spouses a clean break and turns a disputed number into a market price. Both of you must sign the sale mandate and the deed, so agree on the asking price and the agency before listing. Selling a jointly owned apartment in Paris (opens in a new window) goes more smoothly with one agency and a price you have both approved in writing.
Tax matters here. The sale of your main home is exempt from capital gains tax. The spouse who moved out can keep that exemption, as the French tax administration's guidance (opens in a new window) explains, on two conditions: the other spouse lived there until the flat was listed, and the sale happens within a normal timeframe.
Overpricing can break that timeframe. In one case, the tax authority refused the exemption: the spouses had moved out years before the sale, and the flat, bought for about €167,700, had been listed at €880,000 and then €850,000. A realistic valuation protects your tax position as well as your sale.
3. Keep the property in joint ownership for now
Some couples keep the flat in joint ownership (indivision) for a while, for instance until the children finish a school year or the market firms up. It can work, but only with clear rules.
Put in writing who pays the loan, the service charges and the taxe foncière, and whether the spouse living there owes the other an occupancy payment. The law treats one spouse's use of the family home as free only until the divorce petition, unless the judge decides otherwise.
Watch the tax effect if the flat stops being anyone's main home. Paris applies a 60% surcharge on the taxe d'habitation for second homes. The IFI wealth tax applies above €1.3 million of net property assets, and spouses who are divorcing and authorised to live apart file separately.
Remember too that the value will be refreshed at the eventual division. The figure you agree today is not frozen.
4. Rent out the property instead of selling
Renting can cover the loan while you decide, but it is not always possible, and it is rarely simple. Check four things first:
- Consent: with two owners in equal shares, in practice you both need to agree to the lease and its terms.
- Energy rating: G-rated homes cannot be newly let, and F-rated homes join them in 2028.
- Rent rules: Paris applies rent control, with strict limits on reference rents and supplements. The team at Relocation in Paris explains how rent control works in Paris (opens in a new window) for owners weighing this option.
- Tax and financing: rental income must be declared in France, and your loan may require your bank's agreement before you let the flat.
There is also a tax trap. Renting out the former family home before selling can put the departing spouse's capital gains exemption at risk, because that exemption relies on the other spouse living there until the flat is put on the market. Talk to your notaire before signing any lease.
5. How to decide which option makes the most sense
No option fits every couple. These criteria usually point the way:
- Cash needed now: a sale releases cash fastest, while a buyout requires it.
- Affordability of the buyout: can the spouse who stays finance the soulte and the full loan within the 35% limit?
- Mortgage position: if the loan is close to or above the value, selling or waiting may be safer than a buyout.
- Whether either spouse still needs the home: school continuity for children often favours a buyout or temporary joint ownership.
- Rental potential: only relevant if the DPE, the rules and both owners allow it.
- Expected sale timing: a long sale can put the capital gains exemption at risk and delay the division.
- Tax and legal implications: partition duty, capital gains, IFI and the second-home surcharge each favour a different path.
If the spouse who leaves plans to stay in Paris, the next step is often buying your next home in Paris (opens in a new window), or renting first. For the rental route, Relocation in Paris has an English guide on how to rent an apartment in Paris as a foreigner (opens in a new window).
How Is a Paris Apartment Valued During a Divorce?

A Paris apartment is valued mainly by comparing it with recent sales of similar flats nearby, then adjusting for surface, floor, light, building condition and energy rating.
The arrondissement average is only a starting point. At the start of 2026, the average price of older apartments in Paris stood at €9,600 per m², according to the Notaires du Grand Paris. Two flats a few streets apart can sit far from that figure in either direction.
Size, floor, light and layout
Surface comes first, but in Paris it means the loi Carrez surface: the private floor area of a copropriété lot, excluding spaces under 1.80 m high. If the real Carrez surface turns out more than 5% smaller than stated, the buyer can claim a proportional price cut within a year, so valuers work from the certified figure.
Position within the building comes next. A third floor with a lift and a street-facing balcony often behaves very differently from the same surface on a sixth floor without a lift, or a ground floor overlooking a dark courtyard. Layout matters as well. A through apartment with windows on both sides, or a kitchen that can be opened up, widens the pool of buyers.
In central arrondissements, annexes add real value: a cellar, a parking space, or a maid's room (chambre de bonne) on the top floor.
Building condition and planned works
The building can move the value as much as the flat itself. Valuers read the copropriété minutes to see what has been voted, such as façade restoration (ravalement), roof repairs or a new lift. Large voted works that are not yet paid can lower what a buyer will offer.
In a buyout, decide explicitly who carries these costs. It is a frequent source of later friction (more frequent than couples expect), because the spouse who keeps the flat inherits the future bills.
DPE and energy performance
The DPE energy rating now affects resale value, mainly because of the rental calendar set by the loi Climat et Résilience. Homes rated G have been barred from new lettings since 1 January 2025. F-rated homes follow on 1 January 2028 and E-rated homes on 1 January 2034. Investor buyers price that in.
Owners of electrically heated flats may get better news. Since 1 January 2026, a revised conversion factor for electricity in the DPE calculation (opens in a new window), cut from 2.3 to 1.9, has lifted some flats out of the lowest classes without any works. If your flat has electric heating and an older DPE, ask whether an updated certificate would change the rating before the valuation.
Why micro-location matters more than the arrondissement average
Prices vary more within arrondissements than most owners expect.
- By neighbourhood (late 2025): the notaires' standardised prices ranged from €6,640 per m² in the Goutte-d'Or area of the 18th to €15,970 per m² around Notre-Dame in the 4th.
- By arrondissement (early 2026): from about €7,530 per m² in the 19th to more than €14,000 in the 6th.
A valuer who knows the specific street therefore matters more than one who quotes the district average. The notaires' interactive map of Paris property prices (opens in a new window) shows prices by neighbourhood, which helps you ask sharper questions during the visit.
Why the purchase price may not reflect today's value
Many couples bought near the 2021-2022 peak, and their flat may be worth less today. The Notaires-Insee indices show Paris apartment prices falling by about 10.1% since the market turned in 2022, an average loss of around €57,700 per apartment. Paris flats resold after three years recorded an average loss of 8.9%, about €50,350 on a 53 m² apartment.
Prices have since steadied. In April 2026, older Paris apartments stood at €9,530 per m², up 0.4% over a year. But steady is not the same as recovered.
The purchase price is not the reference in a divorce. Today's market value is.
How to Get a Paris Property Valued for Divorce From Abroad

You can get a Paris property valued for divorce from abroad by arranging access and documents remotely, choosing an English-speaking valuer, and working with the notaire through a power of attorney. The valuer still needs to visit the flat in person.
Step 1: Arrange the valuation remotely
Most of the work happens by email and video: sending the file, agreeing the brief, reviewing comparables, discussing the draft. The visit is the exception. Someone has to open the door, whether it is the spouse still living there, a relative, the building caretaker (gardien) or a trusted local contact.
Build time zones into the plan. A decision that needs two spouses, two lawyers and a notaire spread across New York, London and Paris rarely happens in a single day. Diplomats and embassy staff often face the added pressure of a posting schedule, so start the valuation as soon as the separation is clear.
Step 2: Make the valuation useful for advisers abroad
A French valuation often has to work in a foreign court or settlement. A few details make that easier:
- an English version or summary of the report
- the value converted into dollars or pounds, with the exchange rate and date stated
- a clear description of the method, the comparables and the valuer's qualifications
For couples divorcing in England, English law has no marriage regimes as such. A French notaire will therefore usually treat the couple as married under separation of assets and divide the property according to the English court order. Make sure that order deals with the Paris flat specifically.
A foreign divorce judgment generally produces effects in France without a separate procedure, except where it has to be enforced against property or people. And courts abroad do not always follow French arrangements: in one case, a New York court set aside a French marriage contract and divided the couple's assets under New York law.
Tax follows residence. If a spouse now living abroad sells, capital gains are taxed at 19%, with social contributions kept at 17.2% for property gains in 2026. Sellers covered by an EEA, Swiss or UK social security system pay only the 7.5% solidarity levy instead of the full contributions, and British residents still qualify after Brexit.
Sellers outside the EU and EEA usually need an accredited tax representative when the price exceeds €150,000, unless the gain is fully exempt through the length of ownership. The French tax administration's page on capital gains for non-residents (opens in a new window) sets out the available exemptions. American citizens should also check the US side with a tax adviser.
Step 3: Working with a French notaire from overseas
The notaire's first question will be which law governs your marriage. Couples who married or chose their applicable law after 29 January 2019 fall under the EU matrimonial property regulation. Those married from 1 September 1992 fall under the 1978 Hague Convention, which binds only France, Luxembourg and the Netherlands. The Paris notaires explain these rules in their note on international marriages (opens in a new window).
You do not need to fly in for every step. A power of attorney can let someone sign on your behalf, and some notaires offer remote signing by video, checking your identity against your passport. Documents from abroad may need a sworn translation and an apostille, so start early.
If one of you is moving to or from Paris at the same time, relocation support for the spouse who is moving (opens in a new window) can take care of the practical side of the move while the legal side progresses.
What if the property is owned through an SCI?
If you hold the Paris flat through a property company (société civile immobilière, or SCI), the company's shares are what get valued, not the flat directly. The starting point is still the apartment's market value, adjusted for the SCI's loans and the partners' current accounts.
Transfers of SCI shares follow the company's articles and have their own tax treatment. Business owners who hold property this way should involve the SCI's accountant and the notaire before agreeing any figure. The property valuation itself follows the same steps described above.
How Estate in Paris Can Help Value Your Paris Property
Estate in Paris offers a property valuation service for Paris apartments (opens in a new window), based on the property's characteristics, its location and recent local transactions. The aim is a clear, well-explained view of what your apartment is worth in today's market, from a team that works in these streets and buildings every week.
That valuation can help you understand where the market stands before you discuss next steps with your spouse, your notaire or your legal adviser. If you later decide to sell, or to buy your next home in Paris, the same team can support those steps. You can read how an engagement with Estate in Paris works (opens in a new window) before getting in touch.
FAQ
Often, yes. The Paris notaires say each party can ask a real estate professional, such as an agency or a notaire, for an estimate, and they recommend getting several. If you expect a dispute or a court process, a formal expertise carries more weight.
Conclusion
A home appraisal for divorce in France is less about finding a perfect number than about agreeing one that both spouses, the notaire and, where needed, a bank can rely on. In Paris, that figure turns on details: the Carrez surface, the floor, the building's voted works, the DPE rating and the exact street.
You now know who can value the property, what each option costs, how the valuation date works, and what the figure means for a buyout, a sale, joint ownership or a rental. The next step is practical. Gather the title deed, the diagnostics and the copropriété documents, then get at least one professional valuation from someone who knows your part of Paris.
If one of you lives abroad, put the language, currency and power-of-attorney questions into the plan from the start. They take longer to solve than the valuation itself.